

Cash Advance - No credit Check

- 2.84K Reviews
- 4.7
- Downloads
- 500,000+
Our take on Cash Advance - No credit Check from Appgk
When an unexpected bill lands before payday, the appeal of a cash advance app is obvious: you want to see whether a short-term option might help without spending an afternoon comparing complicated financial products. I tested Cash Advance - No credit Check with that situation in mind, paying attention not only to how quickly its main flow feels, but also to whether it encourages sensible borrowing decisions. My overall impression is that it is best treated as a starting point for exploring emergency cash options, not as a guaranteed solution or a replacement for a proper budget.
This is a free finance app from D.J. Advance App, aimed at adults who need to investigate cash advance possibilities. Its store summary focuses on getting cash while waiting for payday, and the short description reduces the idea to “Cash Advance.” That makes the purpose easy to understand, although the simplicity also means you should approach every result or offer with care. A short path to a financial product is convenient, but convenience should never replace reading the repayment terms.
How the app feels in everyday use
The first thing I noticed is that the app’s value depends less on entertainment or long-term engagement and more on how clearly it helps you move through a financial decision. I would open it with one specific question: “Can I find a realistic short-term option for this expense, and what will it cost me?” That mindset is much safer than opening it simply because the phrase “no credit check” sounds reassuring.
For a realistic example, imagine that your electricity bill is due before your salary arrives and you are short by a modest amount. I would use the app to review the available path, write down the repayment date and total cost, then close it before accepting anything if the numbers did not fit my next paycheck. The useful workflow is to compare the proposed obligation with your existing rent, transport, food and subscription payments. A cash advance that solves today’s problem but creates another shortage next week is not a successful outcome.
Best Parts of Cash Advance - No credit Check
Things to Keep in Mind About Cash Advance - No credit Check
The app is most suitable for someone who already knows the exact amount needed and has a dependable income date. That person can use it as a quick way to explore an option and then make a deliberate decision. It is less suitable for someone who is borrowing repeatedly to cover ordinary monthly expenses, or for anyone who cannot identify how the advance will be repaid. In those cases, a nonprofit budgeting service, a conversation with a bank or credit union, or a payment extension from the bill provider may be a better first move.
I also recommend treating the wording around credit checks carefully. It may make the process sound more accessible, but it does not mean approval is automatic, the cost is low, or repayment is flexible. Those are separate questions. Before continuing, I would look for the actual amount received, the total amount due, the due date, any optional or required charges, and what happens if repayment is late. If those details are not immediately understandable, I would not proceed simply because the application feels fast.
News and Features Related to Cash Advance - No credit Check

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A practical way to use it without losing control
My preferred approach is to prepare before opening the app. Check your bank balance, list the bills due before your next income, and decide the maximum amount you could repay without skipping essentials. Then use the app only to investigate whether a matching option exists. This small preparation step prevents the common mistake of choosing an amount based on what appears available rather than what your budget can support.
A second useful habit is to take notes outside the app. Record the requested amount, the amount you would actually receive, the repayment date and the full repayment figure. Having those details on paper makes it easier to compare the offer with an overdraft, a credit-card cash advance, a local credit union product or a direct payment arrangement. It also reduces the chance that you will forget the commitment after closing the screen.
Don't want to read the full review?
A third tip is to separate urgency from eligibility. If the app presents a route that appears promising, that is not the same as money already being available. I would only plan around funds after the final terms are clear and the money is actually accessible. This distinction matters when a bill is due soon, because assuming that an application will complete in time can leave you with both the original problem and a new repayment obligation.
What the current release tells me
The current version is 1.1.3, and the app supports devices running Android 7.0 or later. That gives it a relatively broad reach for people using older Android phones, which is a practical advantage for a finance tool intended to be accessible. I would still keep the operating system updated where possible, use a screen lock, and avoid reviewing sensitive financial information on a shared or public device.
Screenshots
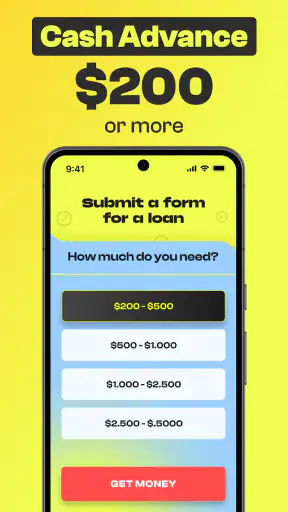
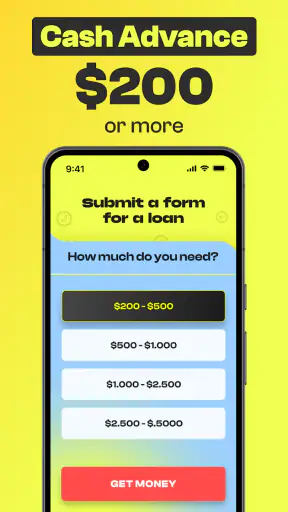
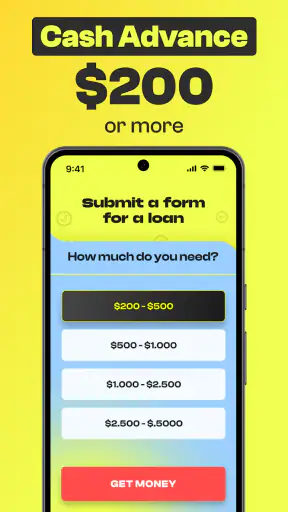
The app was released on December 5, 2022, so it is not a brand-new experiment. It has built a visible audience, with more than 500 thousand installs, an average rating of 4.7 from around 35 thousand ratings, and roughly 2.8 thousand written reviews. Those figures suggest that many people have found the app worth trying, but they should not be mistaken for proof that every user receives the same terms or outcome. Financial suitability is personal, and popularity cannot tell you whether a particular advance is affordable.
From a product-evolution perspective, version 1.1.3 is the release I would judge today rather than relying on early impressions. The important question is whether the current flow remains understandable when you are under pressure. A later version number does not automatically mean better financial transparency, so I would still inspect every screen and confirmation step instead of assuming that the app’s maturity guarantees a smooth experience.
Existing users may appreciate not needing a modern flagship phone to access the current release. That matters if you keep a backup handset or use an older device for budgeting. On the other hand, users who expect a full personal-finance dashboard, detailed spending categories or long-term debt management may find the experience too narrow. Its identity is centered on cash-advance discovery, not on replacing a complete banking app.
Where it compares well with usual alternatives
Compared with searching the web for short-term lenders, a dedicated app can feel more focused and less exhausting. You begin with a clear purpose instead of sorting through unrelated pages. Compared with asking your bank about an overdraft, the app may feel more approachable to someone who wants to explore an alternative first. That lower friction is the main reason I can see people choosing it.
However, lower friction is also the main trade-off. A bank, credit union or employer-based advance program may provide clearer account history, established support channels or a more familiar repayment structure. A direct conversation with the company you owe may even remove the need to borrow at all. If a utility provider can move a due date or split a bill at little cost, that option is usually worth checking before accepting a cash advance.
Traditional credit products can also be better for planned expenses. If you need money for several months rather than until the next paycheck, a structured personal loan with transparent installments may be easier to budget. I would not use this app to finance a holiday, a large purchase or an ongoing subscription habit. Its strongest use case is a short-lived cash gap with a clearly identified repayment source.
The app should also not be confused with free money. “Free” describes the app’s price, not necessarily the cost of any financial product you may encounter through it. That distinction is important enough to repeat in practical terms: downloading or using the app may not cost you, while borrowing through a provider can involve charges or other obligations. I would judge the offer, not the download price.
Questions I would answer before accepting anything
The first question is whether the app itself sends money or helps connect you with another provider. I would determine exactly who would be responsible for the agreement before entering sensitive details or accepting terms. The name shown on the final agreement matters because that is the party whose repayment rules, customer support process and disclosures you need to understand.
The second question is how much the advance really costs. I would not rely on a single headline figure. I would compare the amount deposited with the total amount withdrawn later, then check whether the repayment date lines up with my income. If the numbers are difficult to locate or written in a way that makes comparison awkward, that is a strong reason to pause.
The third question is what happens if my paycheck is delayed. A plan that works only under perfect timing is fragile. Before accepting, I would look for information about late repayment, failed withdrawals, extensions and customer support. I would also leave enough money for food, housing and transportation rather than committing my entire next paycheck.
The fourth question is whether I am using the app because of a one-time emergency or because my budget is consistently short. A one-time gap may be manageable with careful repayment. Repeated use points to a deeper problem, and another advance can make that problem harder to escape. In that situation, I would prioritize a spending review and outside financial advice over another quick application.
Remaining gaps and points of friction
The biggest limitation is inherent to this kind of app: speed can encourage decisions before the user has considered the full consequences. The store-facing message is easy to grasp, but a simple promise of access cannot answer the questions that matter most, including total cost, timing and repayment risk. I therefore see the app as a discovery tool that requires active skepticism from the person using it.
Another limitation is that it may not satisfy people looking for broader financial control. I would not choose it as my main budgeting system or as a way to track every account. Someone who wants spending alerts, savings goals and recurring bill planning should look for a dedicated budgeting or banking solution. Combining tools can be sensible, but this app should not be expected to perform jobs outside its narrow purpose.
There is also a privacy responsibility on the user’s side. Any finance-related application deserves careful attention to the information requested, the identity of the provider and the permissions shown during installation or use. I would read each request rather than tapping through automatically, and I would avoid sharing more information than the application or financial process genuinely requires. If a request feels unrelated to the cash-advance purpose, I would stop and investigate before continuing.
The Everyone content rating makes the app broadly accessible from a store perspective, but that does not mean every financial decision inside it is appropriate for every person. Young or financially inexperienced users may need help from a trusted adult or adviser before entering a borrowing agreement. Accessibility and financial readiness are different things, and I would keep that distinction in mind when recommending it to someone else.
What I would watch in future updates
For future releases, I would watch for improvements that make the cost and repayment timeline impossible to miss. Clear side-by-side figures, plain-language explanations and a deliberate review screen before acceptance would make a meaningful difference. I would also value a stronger way to distinguish an initial application from a completed advance, because users under pressure can easily confuse the two.
I would pay attention to how the developer, D.J. Advance App, handles version changes affecting older Android devices. Continued support for the current minimum system would help people using older phones, while transparent update notes would make it easier to understand whether a change affects the application process, account security or presentation of terms. For a finance app, clarity about changes is more important to me than flashy interface additions.
I would also watch whether the app becomes more useful after the immediate emergency. A responsible reminder to record the due date, a simple repayment checklist or guidance on comparing alternatives could help users avoid repeat borrowing. Those additions would not replace financial advice, but they could turn a quick application into a more careful decision-making process.
At the same time, I would not judge future updates only by speed. Faster screens are welcome, but speed without better explanation would not solve the central risk. The best evolution would preserve the app’s accessible entry point while giving users more context before they commit to anything.
My recommendation for the right user
I would recommend trying Cash Advance - No credit Check if you have a specific, short-term cash gap, a reliable repayment date and the patience to inspect every term. Its free entry point, broad Android compatibility and focused purpose make it convenient to explore. The strong user response, including a 4.7 average and a substantial install base, is encouraging, but I would still make my decision based on the individual offer rather than the app’s popularity.
I would skip it if you need ongoing help managing debt, want a complete budgeting suite, or cannot comfortably explain how repayment will fit into your next income cycle. I would also compare it with your bank, a credit union, an employer option and the company requesting payment before borrowing. Sometimes the least expensive solution is a short extension or payment arrangement, not another financial product.
My final view is cautiously positive. The app can make it easier to investigate a cash advance when time is tight, and the current release remains accessible to people with older Android devices. But its usefulness depends on the discipline of the person holding the phone. Use it to compare a carefully defined option, never as permission to borrow more than your budget can repay. If you keep that boundary, it can be a practical first step; if you ignore it, the convenience becomes the very thing that makes a difficult financial situation worse.
Cash Advance - No credit Check FAQ
What is Cash Advance - No Credit Check?
Cash Advance - No Credit Check is generally presented as a financial app that helps users explore short-term cash advance options without relying solely on a traditional credit check. After installing it, users may be asked to provide personal, employment, banking, and income information so the service can evaluate eligibility or connect them with potential lenders. It is important to understand that the app itself may not guarantee approval or provide funds directly.
Can I really get a cash advance without a credit check?
The phrase “no credit check” can be misleading, so users should read the app’s terms carefully before submitting an application. Some services do not perform a conventional hard credit inquiry, but they may still review income, bank activity, employment details, or other eligibility information. Approval is never guaranteed, and available amounts, fees, repayment dates, and lender requirements can vary significantly between applicants.
How much does Cash Advance - No Credit Check cost?
The total cost depends on the service, lender, loan amount, repayment period, and any applicable membership, origination, express-transfer, or late fees. Some apps are free to download but may connect users with third-party lenders that charge interest or other costs. Before accepting an offer, carefully review the annual percentage rate, finance charges, repayment schedule, and cancellation conditions rather than focusing only on the advertised advance amount.
What personal information does the app require?
A cash advance application may request sensitive information such as your full name, address, phone number, date of birth, employment details, income, bank account information, and identification documents. This data can be used to verify identity, assess eligibility, or match you with lending partners. Before continuing, check the privacy policy, permissions, data-sharing practices, and security information, and avoid entering details through unofficial download links.
Is Cash Advance - No Credit Check safe and legitimate to use?
Safety depends on the specific developer, lender partners, permissions, and terms associated with the app. Before downloading, verify the publisher, read recent user reviews, inspect the privacy policy, and confirm that the application is available through the official Google Play Store or Apple App Store. Never pay an upfront fee to unlock an alleged guaranteed loan, and be cautious of requests for unnecessary access to contacts, messages, or unrelated device data.











